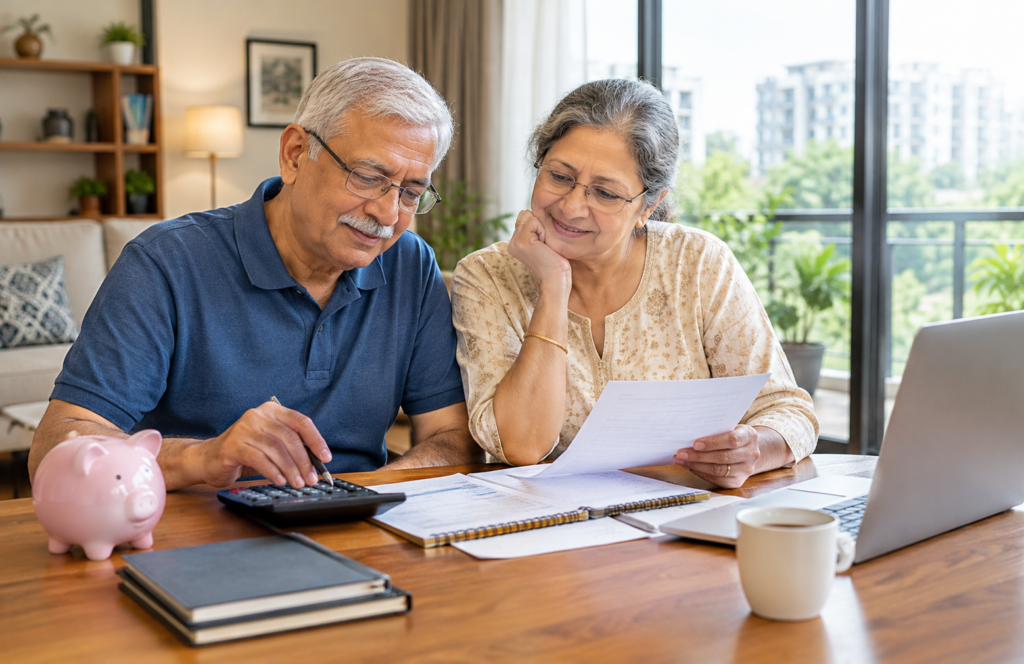
A retired uncle once showed me his budget on the back of an old electricity bill. Flat price, written big. Everything else, nothing. “Baaki toh ho jayega,” he said.
It didn’t quite say “ho jayega.” Within a year, the maintenance, the medical expenses and the little upgrades had eaten into his savings in a way he hadn’t planned. He was fine in the end, but he lost sleep for months, and that’s the part I want you to avoid.
Buying senior citizen apartments is not like buying a flat at thirty. At thirty, you have thirty more years of salary to fix your mistakes. After sixty, your savings have to do the work, and there’s no second chance to earn it back. So the budget needs more thought, not less.
Start with monthly life, not the flat price
Most people begin with “how much can I spend on the flat?” I say begin the other way. Ask what your monthly life will cost in this new home, and then work backwards.
Add up the things you can’t skip: food, electricity, phone, domestic help, medicines, and maintenance charges. Then add the things you enjoy, like travel, gifts for grandchildren, and the occasional restaurant. Then ask whether your pension, rent income and interest can cover this comfortably without touching the main savings.
If the answer is no, the flat is too expensive, however nice the brochure looks.
The money people forget
The flat price is only the first number. Here’s what sits behind it.
Registration and stamp duty can be a big amount, and it varies by state and sometimes by who the buyer is. Check the current rates for your state, because they change. Then come the one-time charges: parking, club membership, power backup, and the “corpus fund” that many societies collect.
The monthly maintenance deserves its own warning. Senior citizen housing apartments usually have more services than a normal society, like a nurse on site, emergency response, common dining or housekeeping. That’s useful, but it also means higher monthly charges. Ask what is included, what costs extra, and who decides when the charge goes up. A low maintenance figure today means nothing if it doubles in three years.
Then there’s furnishing. Good grab bars, anti-skid tiles, proper lighting and a comfortable bed all cost money, and it’s worth spending here rather than saving.
Keep a medical cushion, and don’t touch it
This is the single biggest opinion I hold. Whatever you pay for the flat, keep a separate medical fund that stays untouched. Not “I’ll see if something is left.” A fixed amount in an easy-to-reach account.
Health insurance should be sorted before you move, not after. Premiums rise with age, and some conditions get excluded if you apply late. If you already have a policy, check whether it covers the city you’re moving to, and whether the nearby hospital is in its network. Many people find this out only during an emergency, and that’s a terrible time to find out.
Should you take a home loan?
Banks do give loans to retired people, but the terms are tighter. The tenure is shorter, since lenders look at your age, and they’ll want proof of regular income like pension or rent. Some families take the loan in the name of a working son or daughter, who is often a co-owner.
My personal view is this: if you can avoid a big loan after retirement, do. A monthly EMI that you must pay every month, whatever happens, is a strange thing to carry into your seventies. A smaller flat with a smaller loan, or no loan, often gives more peace than a bigger flat with a heavy one.
If you do take a loan, check the interest rate with two or three banks and read the prepayment terms carefully. Ask your CA about tax benefits, because the rules can change.
Selling your old house
Many buyers of senior citizen apartments fund the purchase by selling their old house. This is where timing matters. Don’t sign for the new flat before the sale money is certain, or you’ll end up borrowing at a bad moment. And if you sell for a profit, there may be capital gains tax, with some relief if the money goes into another house within the time limit. Talk to a CA before you sell, not after. A short chat can save a large amount.
Think about your children, kindly and clearly
Money and family don’t always mix easily, but they should be talked about. Who will own the flat after you? Will it be in a joint name? Is there a will? Registered documents and a clear nomination save children from running around offices later, at the saddest time of their lives.
It also helps to tell them your budget plan. Not to ask permission, but so that nobody is surprised.
A simple way to put it together
Take a plain sheet of paper and make four parts.
One part for the flat and its one-time costs. One for monthly living including maintenance. One for the medical fund and insurance. And one for the free money that’s left for joy.
If the fourth part is empty, the plan is too tight. Retirement should have space for a trip, a gift, a surprise. Otherwise the budget works on paper and fails in life.
A thumb rule I give families: after you buy, you should still have enough to run life for many years without worry, even if returns fall or an emergency comes. If one bad year breaks your plan, the plan is too thin.
What we have learned at Bigchamps
Step into a new phase of retirement and it should feel calm and elegant, with every day a reason to rejoice. That feeling is only possible when money worries stay in the background. Bigchamps doesn’t simply build houses for seniors. We try to build a way of living, and that starts with honest talks about cost.
Read Also: Documents to Check Before Buying a Retirement Apartment in Haryana
When families come to us for senior citizen housing apartments, we ask about their monthly needs and their plans for the years ahead before we talk about floors and views. Sometimes the right advice is a smaller home, or waiting a little. We would rather you buy the right thing slowly than the wrong thing fast.
FAQs
1. How much should I spend on senior citizen apartments compared to my savings?
There’s no single number that fits everyone. A safe approach is to buy a home that leaves you with enough to cover your monthly life and a separate medical fund, without depending on selling something in a hurry. Sit with a CA and work it out for your own case.
2. Are monthly maintenance charges higher in senior citizen housing apartments?
Often yes, because of extra services like emergency help, a nurse or housekeeping. Always ask for a written list of what the charge covers and how it can change in future.
3. Can a retired person get a home loan for senior citizen apartments?
It’s possible, but banks usually give shorter tenures and look closely at pension or other regular income. Some families apply along with a working child as co-borrower. Compare a few banks before choosing.
4. Do I need to buy health insurance before moving in?
Yes, ideally before. Getting cover later can cost more or exclude existing conditions. Check that the hospital near your new home is in your insurer’s network.
5. Should I sell my old house to buy a senior citizen apartment?
Many people do, and it can work well. Just keep the timing in mind and speak to a CA about capital gains tax before you sell. Don’t commit to the new flat until you’re sure of the sale money.